
How This Year’s Midterm Polling is Different From Past “Blue Wave” Elections in One Very Specific Way
A few weeks back, Amy Walter at The Cook Political Report posted on social media that 2026 “feels like déjà vu” if one were to recall the contours of the 2006 midterm elections. She cited similarly low job approval ratings between Donald Trump now and George W. Bush then, similar generic ballot leads for Democrats in both cycles, unpopular Middle Eastern wars in Iran now versus Iraq then, and multiple members of the Republican majority in Congress being linked to sexual misconduct scandals. Perry Bacon Jr. and Patrick Ruffini both recently noted in a piece in The New York Times that the political environment is worse for Republicans than in the 2018 midterms, and current data suggests that current trends signal a “2018-ish blowout in the House.” I’ve recently written about the comparisons of this midterm cycle to 2018 and argued Democrats should be doing better given the national environment is worse than it was for Republicans eight years ago.
Both comparisons seem appropriate and apt: as Amy Walter notes, the landscape now is remarkably similar to 2006; the 2018 midterms are as close to an apples-to-apples comparison as you can get given it was the other midterm taking place in the middle of a Trump term.
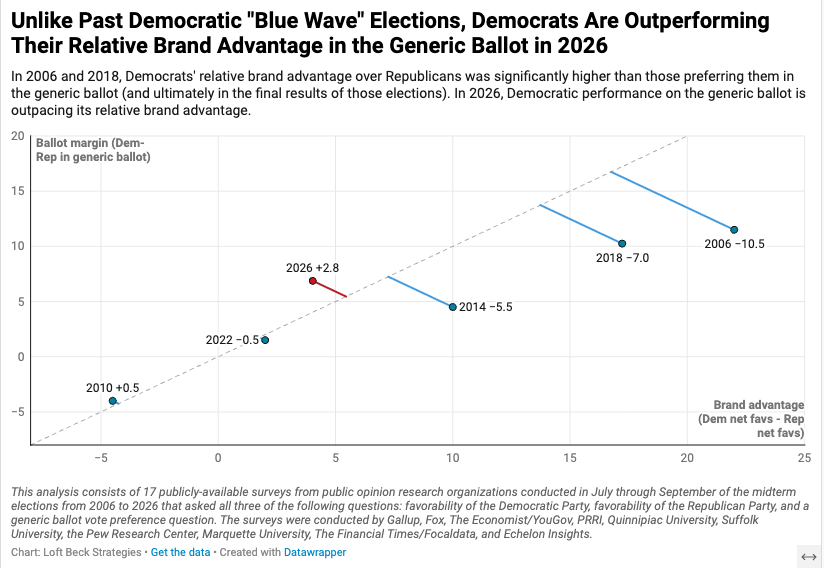
That being said, in one very specific way, 2026 is unlike any midterm since and including 2006, Current generic ballot polling for Democrats is overperforming their relative brand advantage over Republicans, while the 2018 and 2006 midterms saw significant Democratic victories where their performance underperformed their brand advantage. What does that mean, you ask? Well…
An Analysis of the Generic Ballot and Political Party Brands This Close to The Midterms From 2006-2026
For the purpose of this analysis1, I pulled together publicly-available surveys from the Q3 period of each midterm from 2006-2026 that asked all three questions: favorability of the Democratic Party, favorability of the Republican Party, and the generic ballot.2 Some brief notes of explanation for the chart below:
The x-axis is “relative brand advantage” (RBA), which calculates how much higher or lower favorability for the Democratic Party is compared to the Republican Party. For example, in 2006, the average net favorability of the Democratic Party was net +13 and the average net favorability of the Republican Party was net -9; thus, the RBA for Democrats was +22. In 2018, the average net favorability of the Democratic Party was net +1 and the average net favorability of the Republican Party was net -16; thus, the RBA for Democrats was +17. In Q3 of 2026, the average net favorability of the Democratic Party is net -13 and the average net favorability of the Republican Party is net -17; thus, the relative brand advantage for Democrats is just +4. This post does not dwell on the deterioration of the Democratic Party brand, of which I’ve also written about extensively and expressed many concerns about, but I will say this: despite having a narrow RBA, favorability of the Democratic Party dropping by a net 26 points over the last two decades is deeply problematic and should not be overlooked.
The y-axis is far simpler: it is just the net share on the generic ballot, where a number above zero indicates greater Democratic vote preference and a number below zero signals greater Republican vote preference.
When charted this way, Democrats have tended to underperform or equal their RBA in the generic ballot (and ultimately, the actual election results).
The Democratic “blue waves” of 2018 and 2006 were very similar to one another: the RBA was greater than +15 favoring Democrats, but voters in surveys of Q3 that year were pointing toward a 7 to 11 point national margin for Democrats in those respective midterms.
In 2014 and 2022—elections where Republicans prevailed but picked up fewer net seats in the House than would be considered a wave election3—the Democratic RBA was still positive, but their generic ballot performance was slightly worse off.
In 2010, the only midterm of the last six where Republicans had a narrow RBA, preference for Republicans in the generic ballot mirrored their RBA.
What makes 2026 polling different is that Democrats are currently overperforming their relative brand advantage on the generic ballot with a narrow 4-point brand advantage, yet they lead on the generic ballot by 7 points.4
Two High-Level Thoughts on What This Means
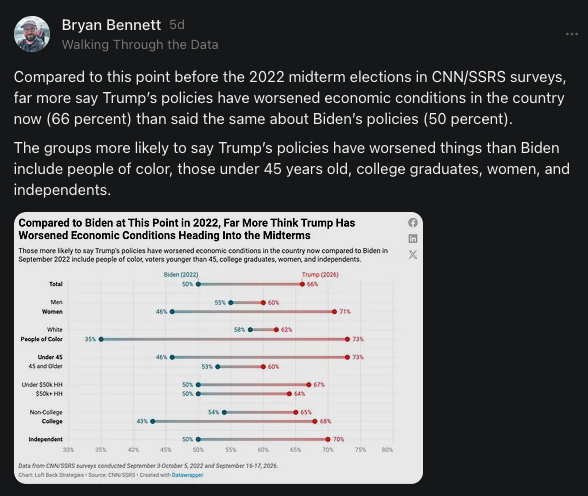
First, this may suggest the Democratic Party brand problems could be holding back their performance in generic ballot polling from being even stronger. After The New York Times/Siena national survey came out a couple of weeks ago showing Democrats with an 8-point national lead, I wrote a post about how they should be doing better than this point in 2018. Another analysis based on the CNN/SSRS survey released last week showed that more voters view Trump’s policies as worsening economic conditions in the country just a few weeks from the 2026 midterms than said the same about Biden heading into the 2022 midterms, with independents and traditionally Democratic-aligned voting blocs (younger voters, women, college graduates, people of color) expressing the greatest levels of dissatisfaction.
Instinctively, this added to my belief that Democrats should be performing several points better than 2018, and to be fair, there have also been several surveys showing double-digit Democratic leads nationally in the month of September, including Emerson (D+11), Marist (D+12), Marquette (D+13), and YouGov (D+14). If something like these results is the actual outcome of the election, that would better align with expectations relative to 2018 (though the current polling aggregations are currently much closer to the 8-point lead in the NYT/Siena survey).
If it does end up being closer to D+8 (or worse), my biggest question will be whether the lack of Democratic RBA and low net rating of the Democratic Party offset the higher antipathy felt toward Trump and Republicans.
Second, I’ll be thinking about the generic ballot as subject to a wider range of error than normal. If you had asked me a few days ago about my opinion regarding potential polling error in one direction or another this cycle, I probably would have said something to the effect of (and in the following order):
Midterm polling in 2018 and 2022 has been fairly reliable in an era where polling has been susceptible to underrepresenting Trump/Republican support in presidential election cycles.
Something akin to Perry Bacon’s point that compared to 2018, we are headed for a blowout at that level (and to be clear, it is really, really hard to get beyond an 8-point national lead!).5
Given those dynamics, there are real challenges to doing this kind of polling accurately, so we should be prepared for a scenario where polling does not match our expectations. Ben Jacobs had a great read where he talked to Zac McCrary, who had exactly the right take: “The issue is that it has never been cheaper or easier to poll the wrong way and more expensive or complicated to poll the right way.”
Moreover, national surveys are hard to make sense of because of the political realities of dynamics like redistricting and how few seats actually determine House control (if it isn’t a total blow out, that is). But state and district surveys are really expensive, have smaller sample sizes, and are often publicly released with incentives that might diverge from depicting the state of the race accurately.
Even if there were systemic polling error underestimating support for Republicans, the current generic ballot lead is probably large enough to where Democrats would still likely win the House (if the error was 2020-sized or less).
All of these thoughts are in relation to the potential of systemic polling error, which is always possible. It is increasingly harder to ignore that possibility when there is almost only good news for Democrats, or when respondents enter a survey and don’t complete it, but have wildly different attitudes on the questions they do answer. As a pollster who has lived through the last three presidential elections, the prospect of non-response bias looms large and will for the rest of my days.
The Democratic RBA versus generic ballot trend introduces a potential of bias within the composition of samples of completed interviews this year. Not one between Democratic candidates and Republican candidates, but between turning out for Democrats and not turning out at all. Democrats led Republicans in the generic ballot in the September Marquette poll by 8 points, which increased to 13 points among likely voters. Similarly, the D+14 survey among likely voters by The Economist/YouGov found a smaller 8-point lead among registered voters. Turnout assumptions are always a necessary part of developing likely voter models; the question sticking with me based on this analysis is whether those assumptions are too rosy for Democrats when many supporting them don’t have a positive view of the Democratic Party either.
At the moment, my gut tells me that the toxicity of the political environment and anger toward Trump and Republicans is more meaningful and motivating than discontent with the Democratic Party and its leadership resulting in depressed turnout.
Maybe this doesn’t mean anything in the end. That said, I am mentally anticipating a larger band of potential outcomes in my head just in case the results in November look different from the generic ballot polling we’re seeing now.
1 This analysis consists of 17 publicly-available surveys from public opinion research organizations conducted in July through September of the midterm elections from 2006 to 2026 that asked all three of the following questions: favorability of the Democratic Party, favorability of the Republican Party, and a generic ballot vote preference question. The surveys were conducted by Gallup, Fox, The Economist/YouGov, PRRI, Quinnipiac University, Suffolk University, the Pew Research Center, Marquette University, The Financial Times/Focaldata, and Echelon Insights.
2 Though some years have as few as two surveys included, their results generally mirror the broader trends on these individual metrics in other surveys asking only a subset of these questions.
3 Of course, 2014 was a wave election favoring Republicans in the Senate. They picked up 9 Senate seats that cycle. Also, 2014 generic ballot polling was a little weird, admittedly: Democrats held the lead in almost every generic ballot measurement over the summer, but it started to break toward Republicans in the fall, and Republicans ultimately overperformed those polls.
4 Though this analysis only uses five surveys from July-September 2026 that measure the generic ballot and the favorability of both political parties, it is akin to the aggregated estimate of the Democratic lead in both FiftyPlusOne (D+7.6) and Silver Bulletin (D+8.8) as of September 28, 2026.
5 The only modern House election by raw vote was 2008 amid the global financial crisis and Republicans being at Peak Unpopular™, when Democrats won by 10.6 points).
